
Market Update: October 19, 2026
For illustrative purposes only. The graphic depicts a general investment approach and is not intended as personalized investment advice. Asset allocation and model selection will vary based on each client's objectives, risk tolerance, financial circumstances, and investment time horizon.
Markets delivered a reminder this week that breadth matters, but so does concentration.
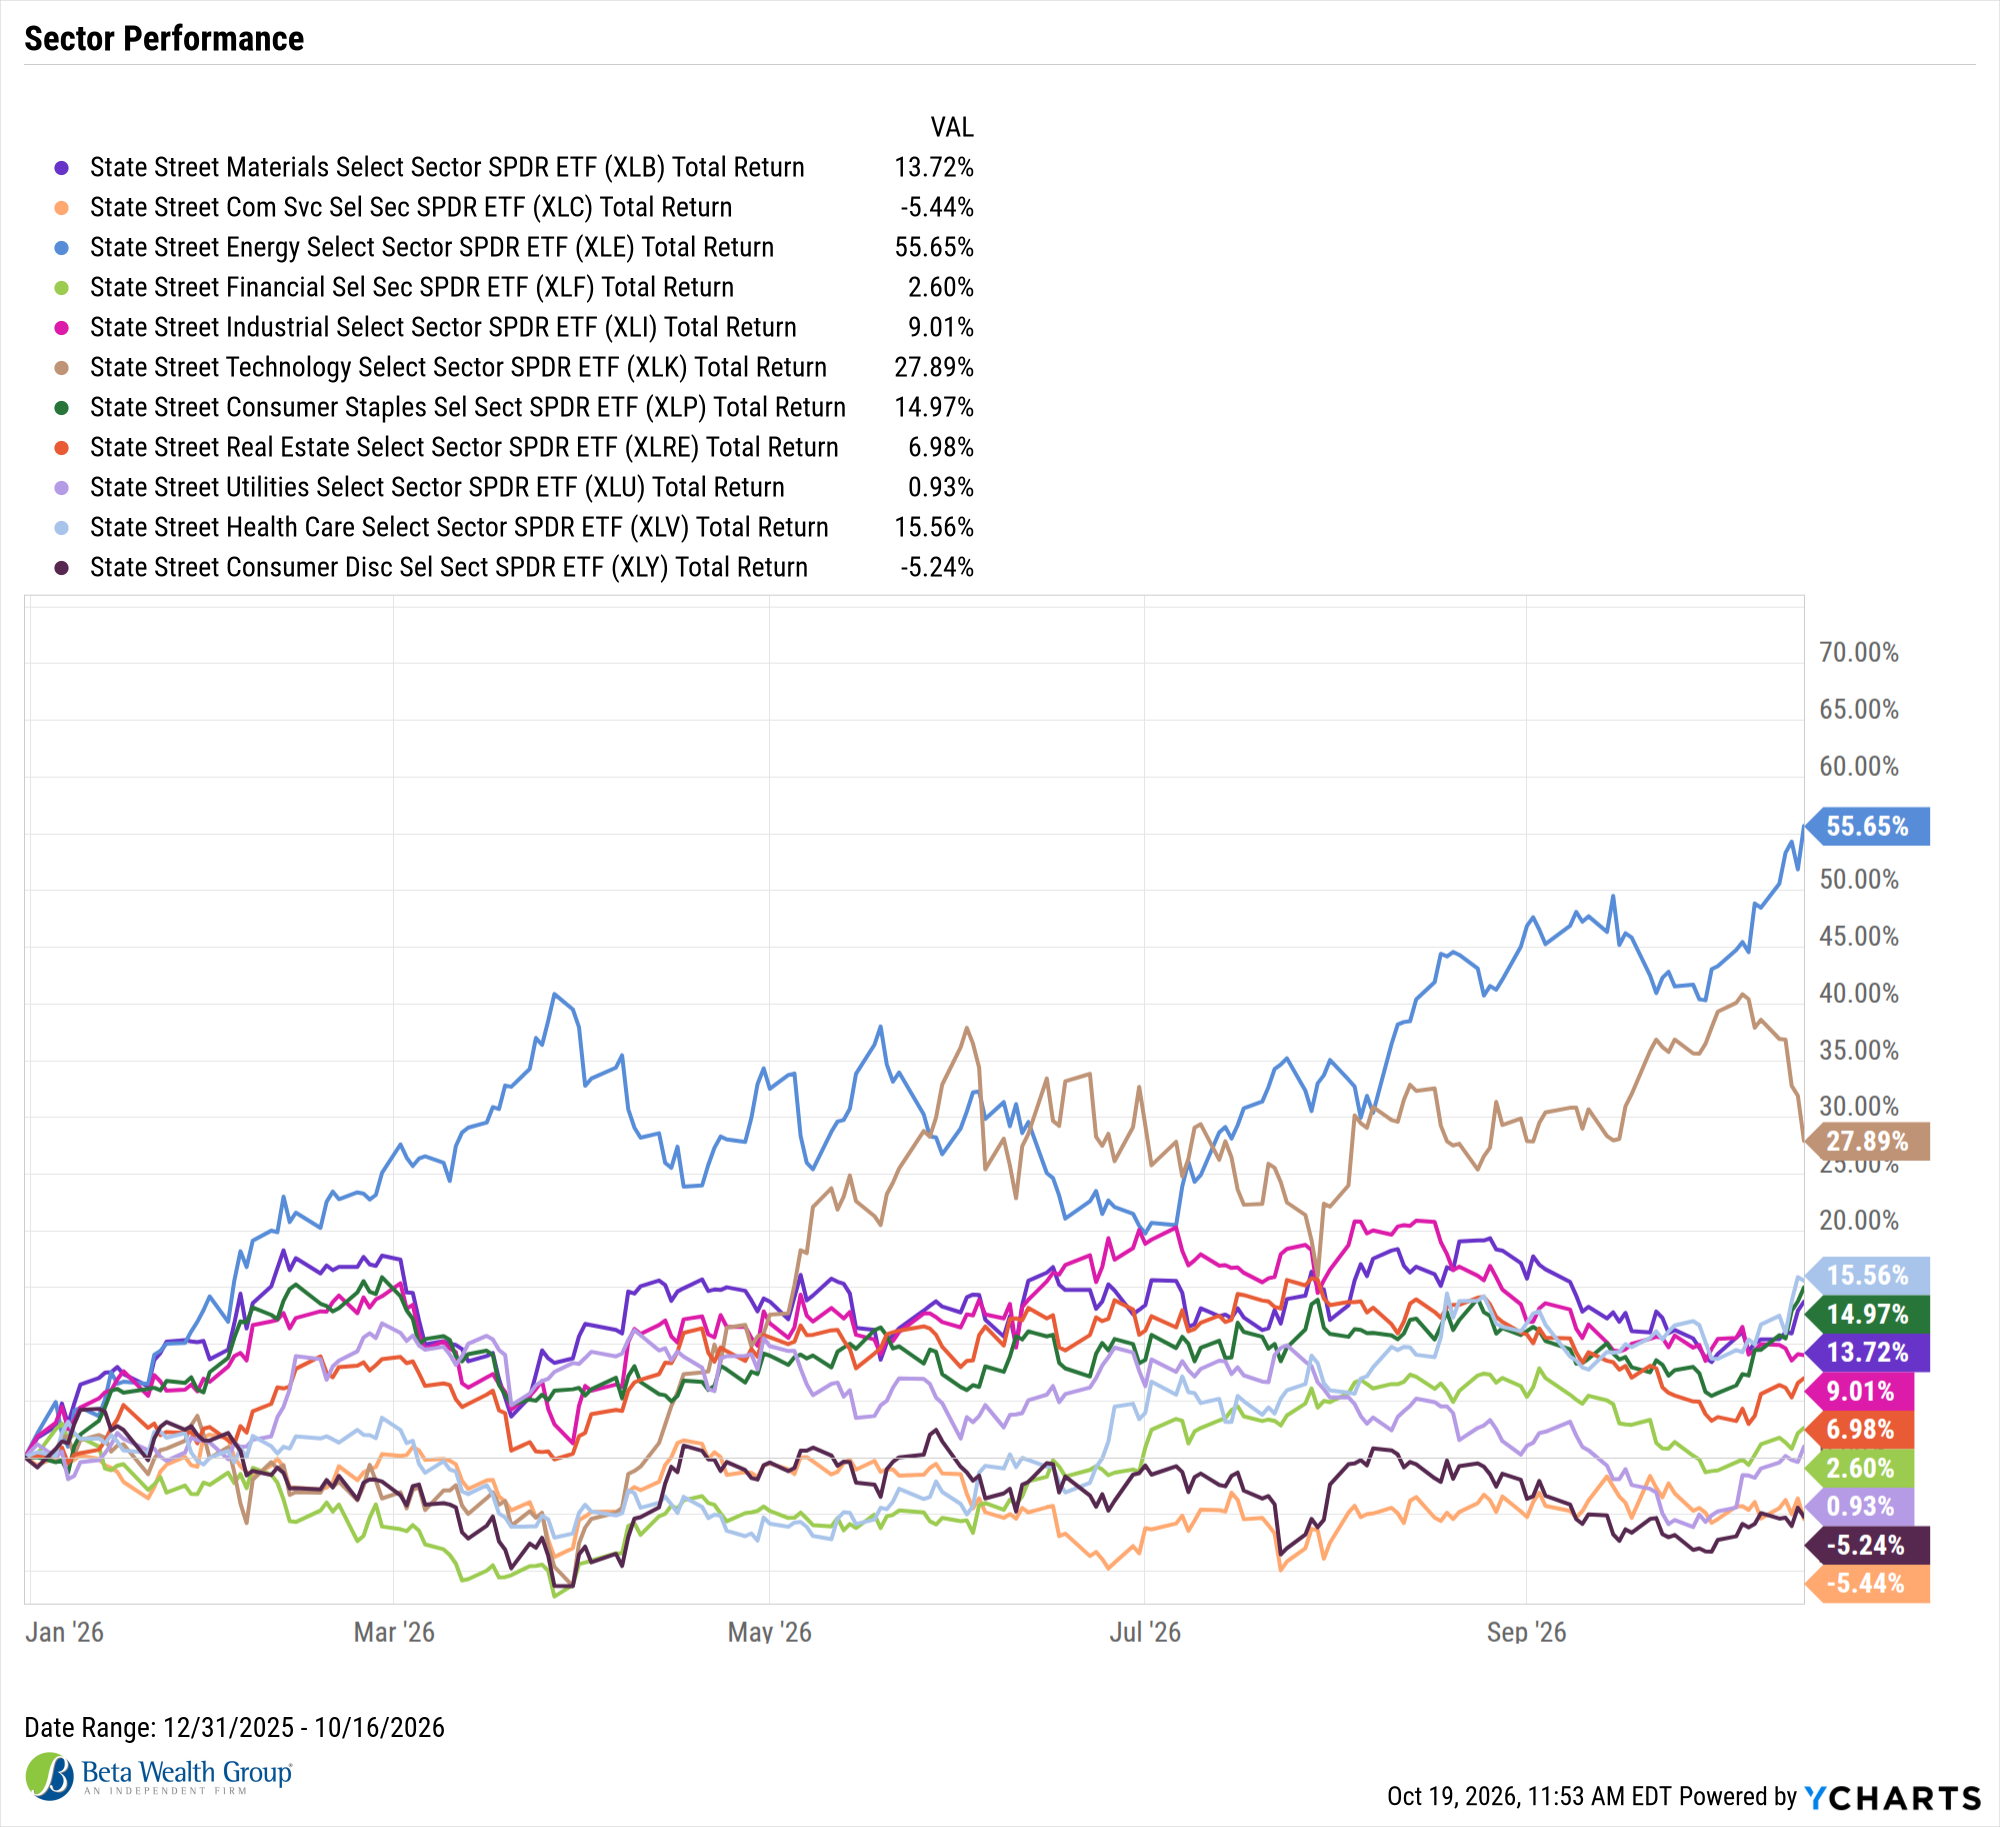
The S&P 500 fell 1.95% as technology losses outweighed gains across seven of its 11 sectors. Despite the pullback, the index remains up 12% year to date.
AI financing concerns weigh on technology
Technology declined 6.4% as investors questioned the financing behind AI infrastructure spending. The focus extended beyond AI’s growth potential to the borrowing costs and balance sheets supporting that expansion.
Sector performance diverges
Consumer staples and energy each gained 5%, followed by health care at 3.4%, materials at 2.5%, and utilities at 2%. Higher crude prices supported energy stocks, with ConocoPhillips gaining 9.3% and APA advancing 7.1%.
Economic resilience meets inflation pressure
US industrial production increased 0.7% in September, exceeding the 0.4% consensus forecast. Initial jobless claims declined to 197,000, while services activity continued expanding.
Elevated services prices and higher energy costs kept inflation risks in focus. Federal Reserve meeting minutes indicated broad support for September’s rate increase, with most officials viewing another hike as potentially appropriate before year-end.
What comes next
Upcoming earnings from Meta, Tesla, Netflix, Procter & Gamble, and other major companies will provide insight into corporate performance and spending plans. Housing data and preliminary October purchasing managers’ indexes will offer additional signals on economic momentum.
This week’s central tension: resilient activity and gains across most sectors contrasted with pressure on highly leveraged AI businesses and persistent inflation concerns.
The information above has been obtained from sources considered reliable, but no representation is made as to its completeness, accuracy or timeliness. All information and opinions expressed are subject to change without notice. Information provided in this report is not intended to be, and should not be construed as, investment, legal or tax advice; and does not constitute an offer, or a solicitation of any offer, to buy or sell any security, investment or other product.